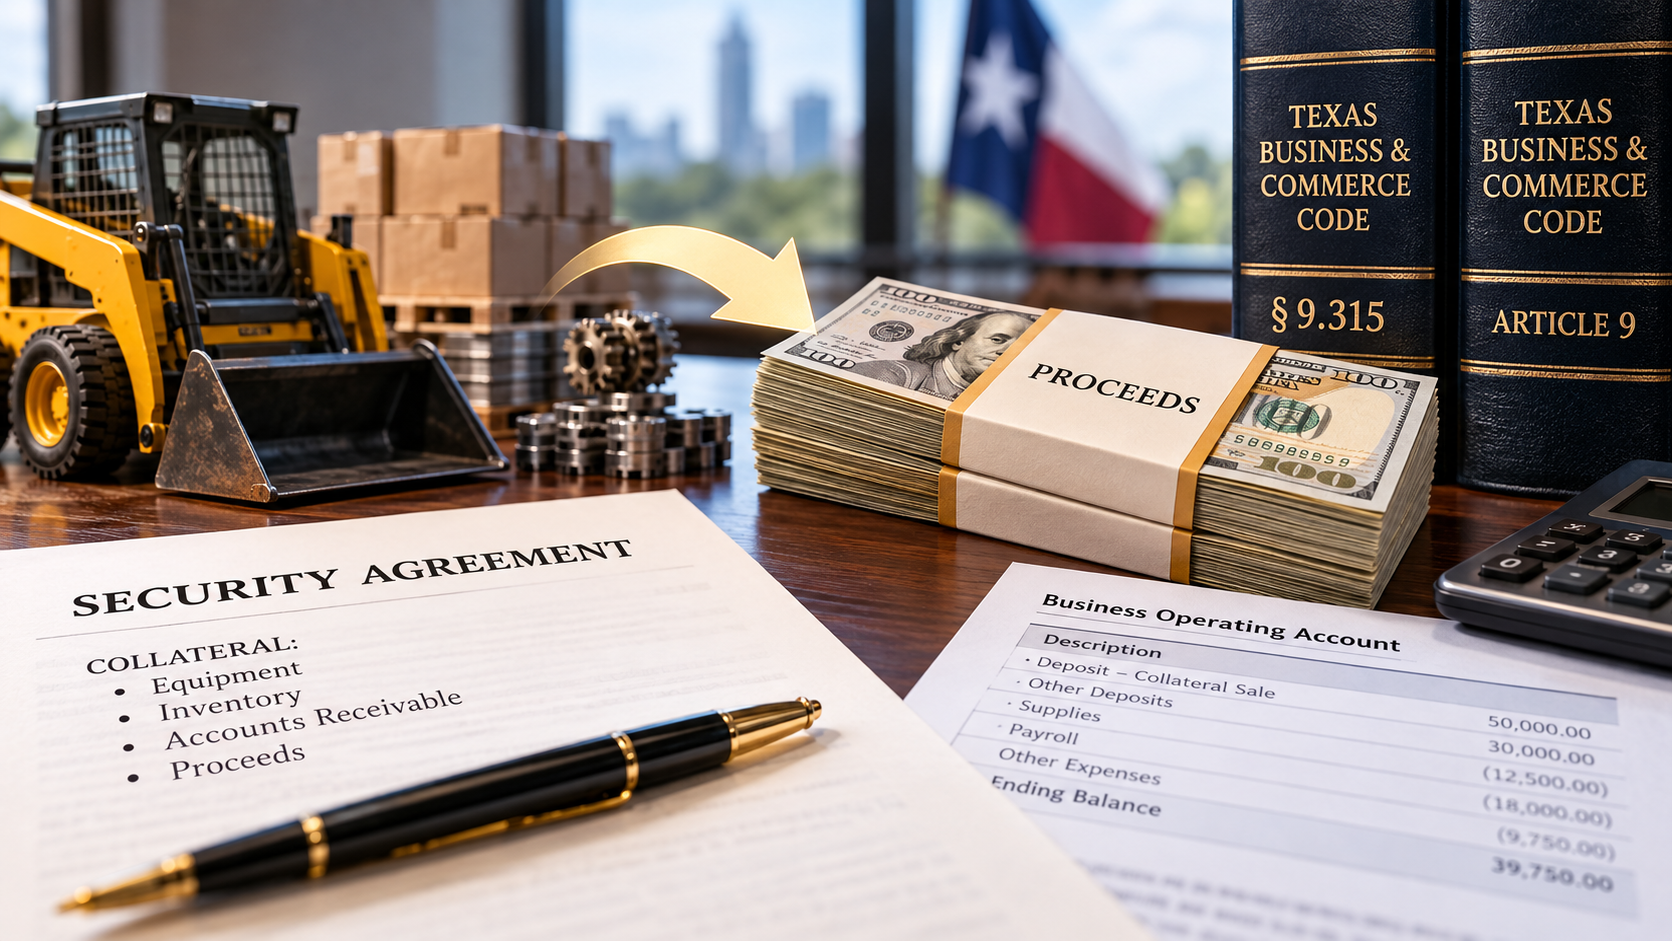
A business borrows $150,000 from a lender and grants the lender a security interest in its equipment and inventory. The lender properly perfects its security interest by filing a financing statement.
Several months later, the business sells some of the collateral, deposits the proceeds into its operating account, and uses part of the money to pay other expenses.
The borrower then defaults.
Can the lender recover the equipment? Can it claim the money received from the sale? What happens if the proceeds have been mixed with unrelated funds or transferred to another person?
These questions implicate one of the more technical provisions of Texas commercial law: Texas Business & Commerce Code § 9.315, which governs the continuation of security interests after collateral is sold and the treatment of proceeds derived from that collateral.
Understanding this statute is important for lenders, borrowers, business purchasers, and attorneys handling secured commercial disputes.
1. What Is a Security Interest Under Texas Law?
A security interest generally gives a creditor rights in specified property to secure repayment of a debt or performance of an obligation.
For example, a business might obtain financing secured by:
- Machinery and equipment;
- Inventory held for resale;
- Accounts receivable;
- Vehicles and other business assets; or
- Certain contractual payment rights.
Chapter 9 of the Texas Business & Commerce Code, Texas's version of Article 9 of the Uniform Commercial Code (UCC), governs many of these arrangements.
A security interest must ordinarily attach to collateral before it becomes enforceable against the debtor. Under § 9.203, attachment generally requires value, the debtor's rights in the collateral, and an appropriate security agreement or another statutorily recognized basis.
Perfection is a separate legal concept. It ordinarily determines whether the secured creditor's interest is effective against competing claimants and affects the priority of that interest.
Many security interests are perfected through a UCC financing statement. Others require possession or control, depending on the type of collateral.
This distinction becomes especially important when the collateral is sold or exchanged.
2. Does a Security Interest Survive the Sale of Collateral?
Under Texas Business & Commerce Code § 9.315(a), a security interest generally continues in collateral after its sale or other disposition unless the secured party authorizes a disposition free of the security interest or another applicable statutory rule changes the result.
Section 9.315(a)(2) also provides that:
"a security interest attaches to any identifiable proceeds of collateral."
This is the central principle underlying the statute.
A lender's security interest does not necessarily disappear merely because the borrower sells the property securing the loan.
Instead, the security interest may continue in the original collateral and attach to identifiable proceeds generated by its disposition.
However, important exceptions apply. For example, Texas Business & Commerce Code § 9.320 generally protects qualifying buyers in the ordinary course of business, and § 2.403(b) addresses certain transactions involving entrustment of goods to merchants.
Consequently, a lender cannot assume that every purchaser of encumbered property takes the property subject to the lender's lien.
The continuation of a security interest in collateral and the attachment of that interest to proceeds are related but distinct legal questions.
3. What Qualifies as Proceeds of Collateral?
Section 9.102(a)(65) broadly defines proceeds to include several categories of property received in connection with collateral.
Depending on the circumstances, proceeds may include:
- Money received from selling collateral;
- Property received in exchange for collateral;
- Rights arising from the disposition of collateral;
- Certain claims arising from damage to or loss of collateral; and
- Certain insurance payments associated with collateral.
Consider a business that grants a lender a security interest in a piece of industrial equipment.
If the equipment is sold for $40,000, the sale proceeds may become substitute collateral under § 9.315.
If the buyer instead transfers another machine in exchange, the replacement machine may also qualify as proceeds.
But identifying proceeds is not always straightforward.
The difficulty increases when the borrower deposits the money into a general operating account, combines it with unrelated funds, and begins making withdrawals.
At that point, the dispute becomes a question of tracing.
4. The Problem of Commingled Proceeds
Suppose a borrower sells secured equipment for $50,000 and deposits the proceeds into an operating account already containing $30,000.
The account now holds $80,000.
Over the following weeks, the business receives customer payments, pays employees, purchases supplies, and transfers money to other accounts.
How much of the remaining account balance is subject to the lender's security interest?
Texas Business & Commerce Code § 9.315(b)(2) addresses this problem by permitting the identification of commingled proceeds through legally recognized tracing methods.
The statute expressly recognizes tracing methods that may include the application of equitable principles.
One approach recognized in tracing jurisprudence is the lowest intermediate balance rule.
Under that approach, funds attributable to collateral proceeds generally cannot exceed the lowest balance reached in the commingled account during the relevant period. Later deposits of unrelated funds ordinarily do not replenish proceeds previously dissipated.
Example: The Lowest Intermediate Balance
Assume the following transactions:
Transaction
Account balance
Existing unrelated funds
$30,000
Deposit of collateral proceeds
$80,000
Subsequent business expenditures
$20,000
Additional unrelated deposits
$45,000
If the account fell to $20,000 before receiving the later deposits, the lender ordinarily could not trace the entire original $50,000 into the account using the lowest intermediate balance approach.
The amount potentially traceable under that approach would be limited to $20,000, assuming the applicable legal and factual requirements are satisfied.
This example illustrates why financial records are often critical in secured-transactions litigation.
Bank statements, transaction histories, accounting records, and testimony concerning the source and use of funds may determine whether proceeds remain identifiable.
Importantly, § 9.315 does not mandate a single tracing formula in every case. The appropriate method depends on applicable law and the nature of the commingled property.
5. The 20-Day Perfection Rule: A Technical Trap for Secured Creditors
One of the most important provisions of § 9.315 concerns the continuation of perfection.
Under § 9.315(c), a security interest in proceeds is initially perfected if the security interest in the original collateral was perfected.
However, that perfection does not necessarily continue indefinitely.
Section 9.315(d) generally provides that a perfected security interest in proceeds becomes unperfected on the 21st day unless one of the statutory exceptions applies.
Those exceptions include circumstances in which:
- A filed financing statement covers the original collateral, the proceeds can be perfected by filing in the same office, and the proceeds were not acquired with cash proceeds;
- The proceeds are identifiable cash proceeds; or
- The secured party perfects its interest in the proceeds through another applicable method within the statutory period.
This distinction can have substantial consequences.
A lender may have a valid security interest against its borrower but lose perfected status against competing claimants.
That can affect the lender's priority and recovery rights, particularly when the borrower has multiple creditors.
Why the Nature of the Proceeds Matters
Suppose a lender holds a perfected security interest in inventory.
The borrower sells the inventory for cash.
If the cash proceeds remain identifiable, § 9.315(d)(2) generally allows the security interest in those proceeds to remain perfected without the lender taking additional perfection steps solely because the proceeds were received.
Now suppose the borrower uses those cash proceeds to purchase a different category of property.
The analysis becomes more complicated. The resulting property may be proceeds, but the continuing-perfection exception for identifiable cash proceeds does not automatically resolve the perfection of a security interest in the newly acquired noncash property.
A secured creditor must evaluate the nature of the new collateral and the available methods of perfection.
The existence of a security interest is not the same as the continued perfection of that interest.
6. What Happens When Proceeds Are Transferred to Someone Else?
Section 9.315 must also be read alongside § 9.332, which protects certain recipients of money and funds transferred from deposit accounts.
Under § 9.332(a):
"A transferee of money takes the money free of a security interest"
The statute contains an important exception where the transferee acts in collusion with the debtor in violating the secured party's rights.
Section 9.332(b) provides comparable protection for transferees of funds from deposit accounts.
Consider a business that deposits proceeds from secured inventory into its operating account and then uses the funds to pay an ordinary supplier.
Even if the lender has a perfected security interest in identifiable cash proceeds, the supplier may receive the payment free of that security interest under § 9.332.
This is an important limitation on a lender's ability to follow money through subsequent transactions.
Otherwise, ordinary commercial payments could expose countless recipients to claims by lenders whose borrowers had previously granted security interests in their assets.
The law attempts to balance secured creditors' property rights against the commercial need for money to circulate freely.
7. What Happens When Two Creditors Claim the Same Proceeds?
Priority disputes can become particularly complicated when multiple lenders have security interests in overlapping categories of collateral.
Suppose:
- Lender A has a perfected security interest in a company's inventory and proceeds.
- Lender B has a perfected security interest in certain other business assets.
- The borrower sells inventory and uses the proceeds to acquire equipment.
- Both lenders claim an interest in the newly acquired equipment.
Determining priority requires more than identifying which lender originally financed the business.
The analysis may involve § 9.315, the general priority rules in § 9.322, purchase-money security interest rules under § 9.324, and other provisions depending on the collateral.
The creditor with the earliest filing does not necessarily prevail in every situation.
The precise collateral descriptions, attachment dates, perfection methods, and applicable statutory exceptions can determine the result.
A proper priority analysis therefore requires examination of the entire secured transaction rather than merely reviewing a financing statement.
8. Why a UCC-1 Financing Statement Does Not Answer Every Question
Businesses sometimes assume that filing a UCC-1 financing statement gives a lender an absolute lien on everything the borrower owns or subsequently acquires.
That assumption is incorrect.
A financing statement is generally a notice-filing instrument. It does not, by itself, create an enforceable security interest.
The underlying security agreement, attachment requirements, collateral descriptions, and perfection rules remain important.
Moreover, even a properly perfected security interest may be subject to:
- Statutory protections for qualifying purchasers;
- Competing perfected security interests;
- Special priority rules;
- Restrictions concerning particular types of collateral; and
- Rules governing the transfer of money and deposit-account funds.
When proceeds are involved, a lender must establish not merely that its financing statement exists, but that the claimed property falls within the security interest and that the relevant perfection and priority requirements are satisfied.
9. Practical Considerations for Texas Lenders and Business Borrowers
For lenders, a properly drafted security agreement should address proceeds, dispositions of collateral, reporting obligations, and the treatment of money received from collateral sales.
Creditors should also evaluate whether their collateral requires perfection by filing, possession, or control.
For borrowers, selling encumbered property does not necessarily eliminate the lender's rights.
A borrower may remain contractually liable for unauthorized dispositions, and the lender may retain rights in the collateral or its identifiable proceeds.
For purchasers of business assets, the analysis is equally important.
Buying machinery, inventory, or other property from a business does not invariably eliminate existing security interests. The buyer must determine whether a statutory protection applies or whether the secured creditor has authorized a disposition free of its interest.
In substantial asset acquisitions, lien searches, payoff arrangements, and written releases can be essential parts of the transaction.
10. Litigation Strategy: Following the Money
When a borrower defaults after disposing of collateral, the lender's attorney should investigate several questions.
First, what property was originally subject to the security agreement?
Second, was the security interest enforceable and properly perfected?
Third, what happened to the collateral?
Fourth, what property or money did the borrower receive in exchange?
Fifth, can those proceeds still be identified through financial records or legally recognized tracing methods?
Finally, has the secured party maintained perfection, and do any competing creditors or protected transferees have superior rights?
The answers may require extensive documentary discovery, including bank records, general ledgers, invoices, purchase agreements, and communications concerning asset transfers.
In appropriate cases, a creditor may also consider provisional remedies or other judicial relief, subject to the applicable procedural and substantive requirements.
The crucial point is that a secured-transactions dispute frequently becomes an accounting and tracing dispute once the original collateral has been sold.
Conclusion: A Security Interest May Follow the Value of Collateral
Texas Business & Commerce Code § 9.315 reflects a fundamental principle of secured lending: the value securing a debt does not necessarily disappear merely because the debtor changes the form of the collateral.
A lender may retain rights in original collateral and acquire rights in identifiable proceeds.
But those rights are not unlimited.
Tracing requirements, perfection deadlines, statutory purchaser protections, and competing security interests can dramatically change the outcome.
For Texas businesses and lenders, understanding these rules before collateral is transferred is considerably easier than litigating their consequences afterward.
David C. Barsalou, Attorney at Law, PLLC, provides legal services involving Texas commercial litigation, contract disputes, secured transactions, and related business matters. Businesses and individuals facing disputes over collateral, financing agreements, or creditor rights may benefit from obtaining legal advice before transferring assets or initiating litigation.
This article is provided for general informational purposes and does not constitute legal advice. The application of Texas secured-transactions law depends on the relevant documents, property, transactions, and circumstances.
At David C. Barsalou, Attorney at Law, PLLC, we help clients navigate business, family, tax, estate planning, and real estate matters ranging from document drafting to litigation with clarity and confidence. If you’d like guidance on your situation, schedule a consultation today. Call us at (713) 397-4678, email barsalou.law@gmail.com, or reach us through our Contact Page. We’re here to help you take the next step.